Same promise. Different price.
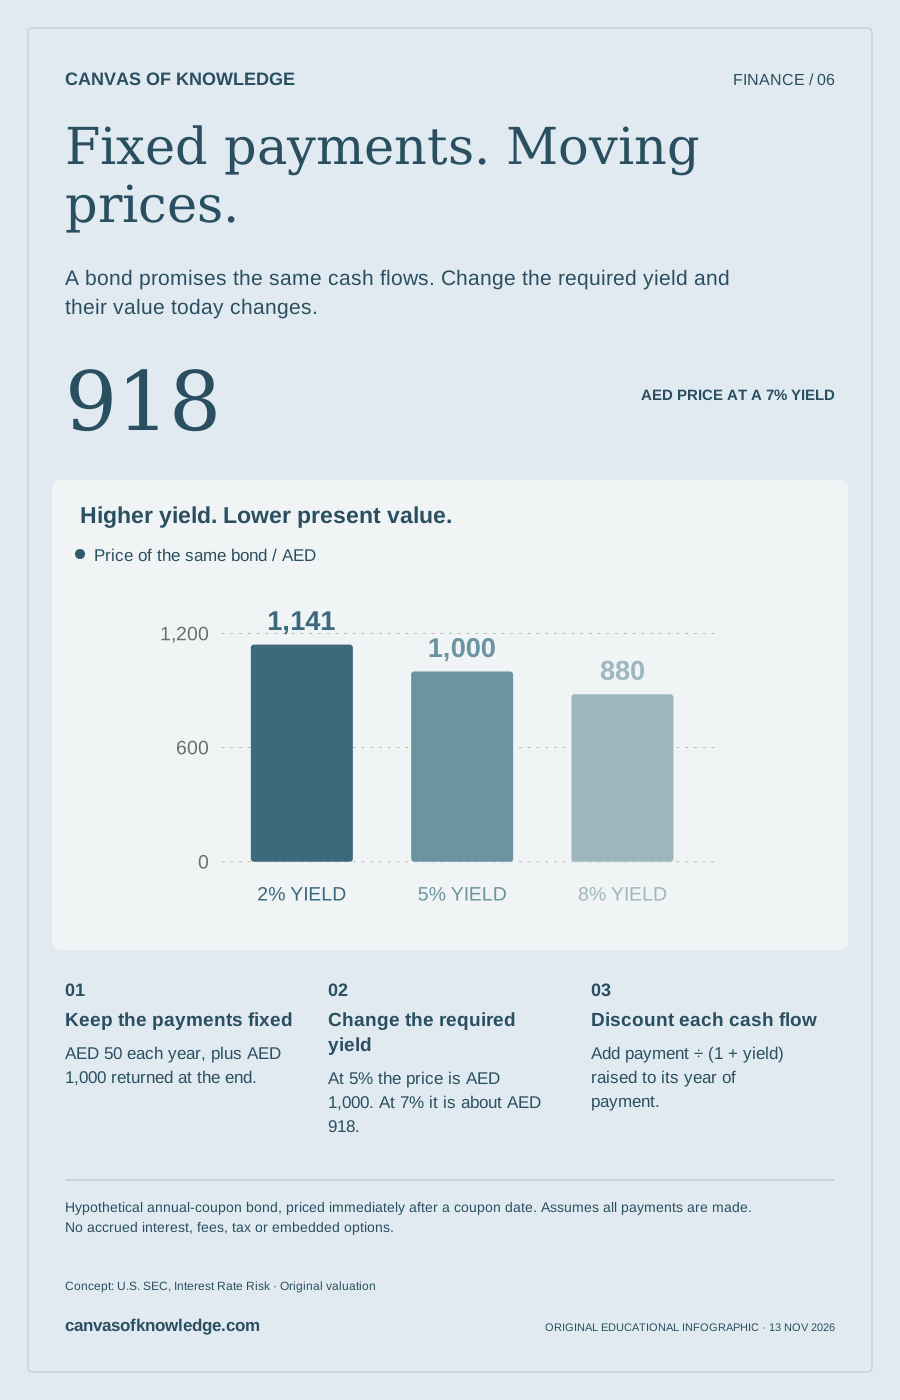
Imagine a bond with AED 1,000 face value that pays AED 50 at each year-end for five years, then returns the face value. At a 5% required annual yield, its present value is AED 1,000. With the same five years remaining, a 7% required yield values those identical payments at about AED 918.
Bring each payment back to today
Divide each payment by (1 + yield) raised to the number of years until it arrives, then add the results. The final payment includes the last AED 50 coupon and AED 1,000 principal. A larger discount rate reduces these present values. The coupon rate is fixed; the yield used to value the bond can change.
Time changes the sensitivity
The explorer holds the annual coupon at AED 50 and lets you change the yield and years remaining. Moving from a 5% to an 8% yield gives about AED 880 with five years left. The tool assumes a valuation immediately after a coupon payment, with the next payment exactly one year away.
Price risk and repayment risk
This model assumes every promised payment is made. Actual bond prices also reflect credit risk, liquidity, embedded options and other factors. Holding to maturity avoids selling at an interim market price, but repayment still depends on the issuer. These are hypothetical valuations, not a current bond quote.
Sources & further reading
Sources checked 13 November 2026. These organisations provide reference material and do not endorse this website.