Start with one sale
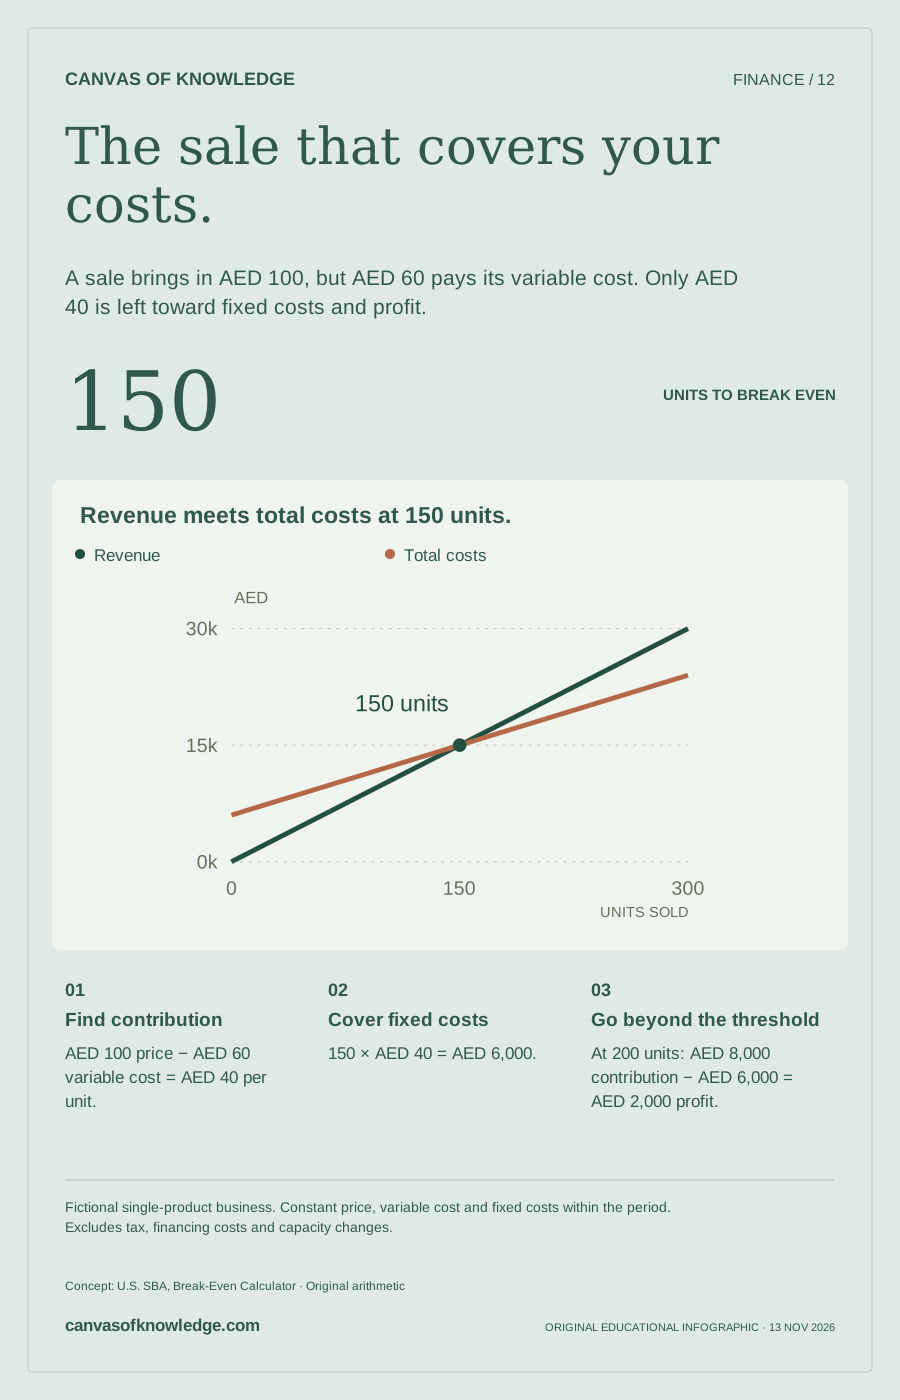
A fictional business sells one product for AED 100. Making and selling each unit costs AED 60 in variable costs. That leaves AED 40 per unit toward fixed costs, then profit. This AED 40 is contribution, not the full AED 100 selling price.
Build the bridge to break-even
Monthly fixed costs are AED 6,000. Divide 6,000 by the AED 40 contribution per unit: 150 units. At 150 sales, revenue is AED 15,000. Variable costs are AED 9,000; adding fixed costs gives total costs of AED 15,000. Operating profit is zero.
The next sale changes the result
At 200 units, contribution is AED 8,000. Subtract AED 6,000 of fixed costs and operating profit is AED 2,000. At 100 units, the same calculation gives a loss of AED 2,000. If the exact break-even quantity is fractional, round up to the first whole unit that covers costs.
Know where the straight lines stop
The explorer assumes one product, constant unit price and variable cost, and unchanged fixed costs in the selected period. It excludes tax, financing costs and capacity changes. If contribution is zero or negative and fixed costs are positive, no sales quantity covers all costs in this model. More demand alone cannot fix that arithmetic.
Sources & further reading
Sources checked 13 November 2026. These organisations provide reference material and do not endorse this website.